Open a trading app and glance at a currency pair — there’s a single number sitting there, looking definitive, as if that’s simply what the market says right now. It isn’t. That number is the end result of liquidity aggregation, and almost nobody using it ever sees the mess it was actually built from.
There Is No Single Market, Just an Illusion of One
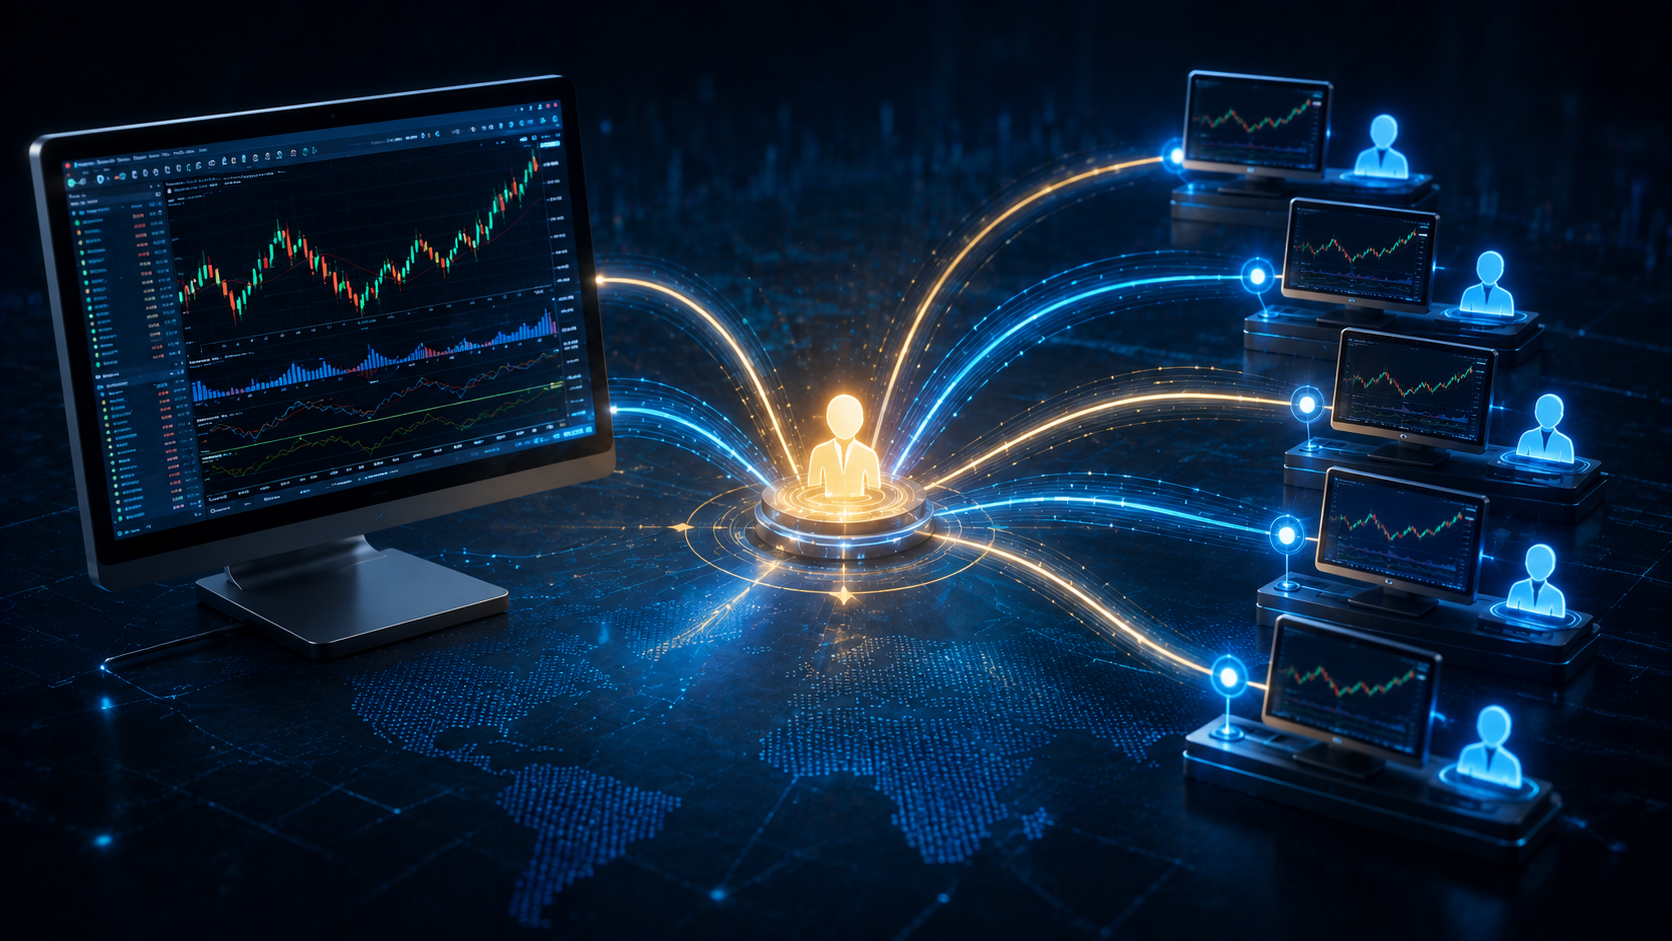
Currency markets don’t have a central price the way a stock exchange does. Dozens of banks and market makers are quoting simultaneously, each one slightly different, each one updating on its own schedule. A trader glancing at their screen has no reason to think about this. The interface hides it on purpose — showing one clean figure is the entire point of the exercise.
But sit with a trader long enough and the cracks in that illusion start to show. Spreads that seem to widen for no reason right before a news release. A price that briefly looks better than it should, then vanishes the instant someone tries to act on it. These aren’t glitches. They’re the visible edge of a system pulling together prices that were never actually unified to begin with.
What’s Actually Happening Underneath
This is what FX liquidity aggregation is solving for. It has to take quotes from providers who don’t agree with each other, some updating every few milliseconds and some lagging noticeably behind, and decide — constantly, automatically — which of those numbers is still worth trusting at any given instant. A quote that was accurate half a second ago might already be stale. Forward it anyway, and a trader ends up trying to execute against a price that’s already gone.
What makes this genuinely difficult is that speed and accuracy pull against each other. React too slowly and the aggregated price lags the real market, costing traders on every fill. React too fast, trusting every incoming quote without verification, and the system starts passing along noise instead of signal — phantom prices that never had real liquidity behind them in the first place.
A few things tend to separate a system that handles this well from one that doesn’t:
- How quickly it identifies and discards a quote that’s gone stale
- Whether it can route across multiple sources without introducing visible lag
- How it behaves when one liquidity provider drops out entirely mid-session
Get any of these wrong, and traders experience it as slippage or a rejected order — something that feels like bad luck but is actually infrastructure quietly failing in the background.
Why It Only Really Matters at Scale
There’s a scale problem that doesn’t show up until volume grows. A small operation can tolerate a clunky aggregation setup because the inefficiencies barely register against low order flow. Once volume climbs, though, every millisecond of lag and every slightly-stale quote starts compounding into real cost. What looked like an acceptable rounding error at low volume becomes a measurable drag at high volume — spread paid that didn’t need to be paid, fills slightly worse than what was actually available a beat earlier.
This is also where the difference between a good and a mediocre setup stops being theoretical. At low volume, almost anything works well enough. At high volume, sloppy quote handling turns into a running cost that shows up in the numbers every single day, even if nobody can point to a single dramatic failure that caused it.
Why None of This Is Meant to Be Visible
A trader shouldn’t have to think about which of forty competing quotes their platform just chose, or why. They should just see a number and trust it’s a fair one. Whether that trust is earned depends entirely on how well the aggregation layer handled everything happening a few layers beneath the screen — sorting through fragments of a market that was never one thing to begin with, and turning it into something simple enough to act on.
Liquidity aggregation is judged almost entirely by its own invisibility: the better it works, the less anyone notices it’s there at all, and the more the price on the screen feels like something solid instead of the constantly shifting compromise it actually is.